
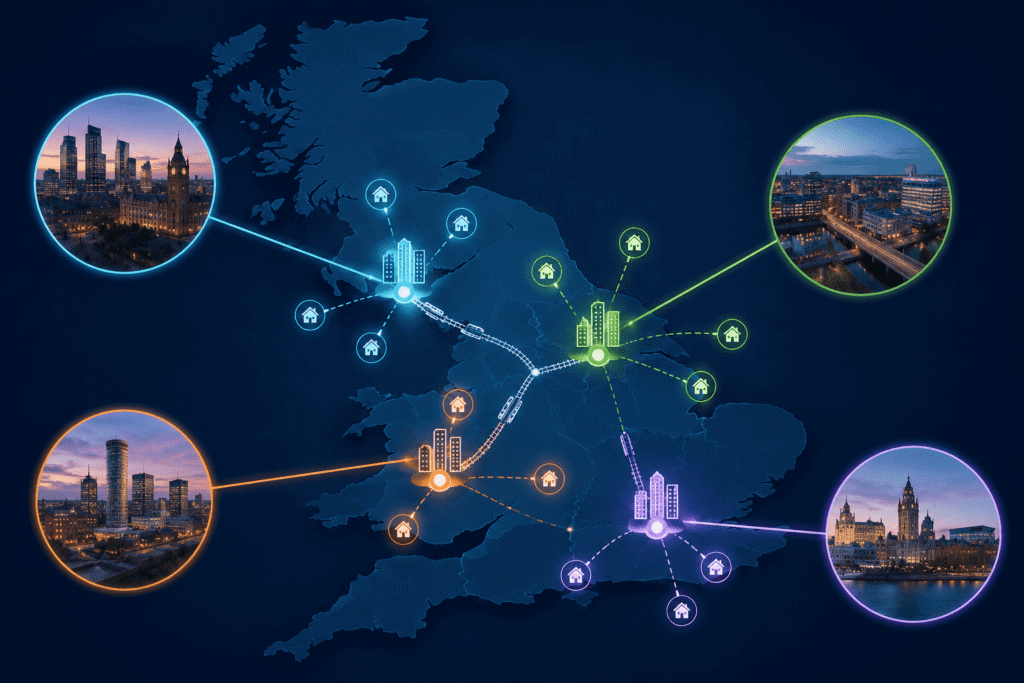
If you’re weighing up where to put your capital this year, you’re not alone. 2026 has brought a genuine shift in where UK property investors are looking, and the answer isn’t as simple as “London” or “the biggest city on the list.” The average UK house price reached £270,000 in April 2026, and average rents hit £1,383 a month in May, both up year on year. But national averages hide the real story. The best UK cities to invest in property in 2026 are the ones where city centre demand and commuter town growth are reinforcing each other, not competing.
That’s the pattern running through every region we’ve researched for this piece: Manchester, Leeds, Birmingham and Liverpool. In each case, the city centre pulls in jobs, students and infrastructure spend, and the surrounding towns absorb the tenants and buyers who get priced out or simply prefer more space, without losing their connection to the centre. Understanding that relationship, rather than picking a single postcode and hoping, is what separates a considered portfolio from a lucky one. If you’re still mapping out how these individual purchases fit into a bigger plan, our guide to building a property portfolio is a useful companion to this piece.
For years, the investor conversation was binary: city centre apartment for yield and liquidity, or suburban house for stability. That divide is breaking down. Property professionals now describe a “hub and spoke” effect, where a strong city centre economy generates demand that simply overflows into the towns along its transport corridors. Stockport is the clearest example anywhere in the country. It generated 70% more buyer enquiries per listing than Manchester itself in recent Rightmove commuter town data, with rents up 16.1% over the past year, driven almost entirely by people who want Manchester-level job access without Manchester city centre prices.
This isn’t a one-off. The same pattern shows up around Leeds, Birmingham and Liverpool, and it’s being reinforced by hybrid working, which has made a 20 to 30 minute commute feel entirely normal rather than a compromise. For investors, the practical implication is straightforward: the best UK cities to invest in property in 2026 rarely mean choosing between the centre and the suburbs. They mean understanding how the two work together, and building a portfolio that can draw on both.
Manchester remains one of the most consistently discussed cities in any conversation about UK property investment, and the fundamentals still stack up. City centre average prices sit around £253,000 to £256,000, with average rental yields in the 5.6% to 6% range, comfortably ahead of most southern markets. Savills has forecast North West house price growth of up to 31.2% by 2029, among the strongest of any UK region, underpinned by the £2.5 billion Bee Network transport overhaul and continued regeneration through Victoria North and Mayfield.
What’s changed is where the growth is actually landing. Stockport, Sale and Altrincham are now described by local agents as benefiting directly from Manchester’s “hub and spoke” pull, with strong city centre demand feeding straight into these commuter markets. Stockport itself is undergoing a £1 billion town centre transformation, sits just 8 minutes from Manchester Piccadilly by train, and was named Best Place to Live in the North West by the Sunday Times. Average flat prices in Stockport town centre (around £175,000, per ONS) remain meaningfully below Manchester’s city centre average, while rental demand keeps climbing.
For investors looking specifically at this corridor, our own Manchester development, One Trafford Edge in Stretford, sits inside the wider £4.2 billion TraffordCity regeneration zone, right in the flow of demand between the city centre and its commuter towns.
Leeds has the largest economy of any city in the north of England outside Manchester, anchored by a financial and professional services sector that employs more than 30,000 people in the city centre alone, with firms like KPMG, PwC and Deloitte maintaining major offices there. The average Leeds house price reached £247,000 in April 2026, with average rents at £1,134 a month, both rising steadily. The £2.5 billion West Yorkshire Mass Transit scheme and the ongoing South Bank regeneration, expected to create 35,000 jobs and effectively double the size of the city centre, are the two big structural stories driving long-term demand here.
Around the edges, Horsforth (LS18) has become the standout example of a “lifestyle commuter” town: strong rail links into central Leeds, consistently high buyer turnover, and enough independent shops and schools to hold onto family tenants long-term. The Wakefield commuter belt, including Sandal, Horbury and Ossett, is showing similar momentum, offering more affordable entry points while staying well within commuting distance. This is precisely the blend of city centre depth and commuter town affordability that makes West Yorkshire one of the best UK cities to invest in property in 2026 for investors who want both yield and growth in the same portfolio.
Our current Leeds developments, Aire Gardens in the South Bank regeneration zone and The One Residence close to Leeds Dock, both sit directly inside this growth story.
Birmingham’s population grew 6.7% between the 2011 and 2021 census, well ahead of most comparable UK cities, and that growth is putting real, sustained pressure on rental supply. The average Birmingham house price sits around £233,000, with prices forecast to rise by as much as 26.4% over the next five years according to recent market analysis. The catalyst has shifted from Commonwealth Games legacy to tangible delivery: the £1.9 billion Smithfield Masterplan and the Curzon Street HS2 hub are now under active construction, not just on the drawing board.
For investors wanting stability alongside growth, Sutton Coldfield stands out as Birmingham’s clearest commuter and family belt, combining strong schools, direct rail links into the city and a level of long-term tenant demand that city centre apartments don’t always offer. Solihull performs a similar role on the southern side of the city. Both benefit from Birmingham’s expanding economic base without carrying city centre price tags.
Our Digbeth development, Digbeth Quarter, sits at the heart of the Smithfield regeneration zone, with HS2 connectivity due to arrive by 2028, right where this growth is concentrated.
Liverpool continues to offer some of the strongest headline numbers of any major UK city. The average house price was £184,000 in April 2026, still 36.9% below the England average, while average rents climbed 6.2% year on year to £901 a month. Rental yields in the strongest postcodes regularly reach 7% to 7.5%. The scale of investment behind this is significant: the £5.5 billion Liverpool Waters masterplan and the £1 billion-plus Knowledge Quarter and Paddington Village scheme are both under active construction, not just planned.
Warrington, sitting almost exactly between Manchester and Liverpool, has built a reputation as the more “defensive” play in this corridor, driven by a diversified employment base around business parks like Omega and Birchwood rather than speculative growth. Wirral and Birkenhead offer the more affordable, higher-yield route into the same regeneration story, with prices still well below Liverpool city centre levels.
Our Liverpool development, Abbey Row, sits within the Knowledge Quarter itself, one of the city’s most active regeneration zones and a strong example of where city centre and commuter demand overlap directly.
None of this points to a single “best” city. It points to a pattern. Across Manchester, Leeds, Birmingham and Liverpool, the strongest performing locations aren’t purely city centre or purely commuter town, they’re the corridors where the two feed each other: fast, frequent transport links, visible regeneration spend, and a tenant base that’s genuinely growing rather than just cycling between existing housing stock.
For investors building a portfolio rather than picking a single purchase, that means thinking in corridors, not postcodes. A city centre apartment gives you liquidity and rental depth. A well-placed commuter town property can give you stronger yield and faster rental growth, often for a lower entry price. Done well, the two complement each other rather than competing for the same capital. If you’re working through how these decisions fit together as a broader strategy, our property portfolio building guide walks through exactly that.
Want to talk through your options with an expert?
Which UK city has the best rental yields in 2026? Liverpool and Leeds are currently delivering some of the strongest headline yields among major UK cities, with several postcodes reaching 7% or higher, while Manchester offers a stronger balance of yield and long-term capital growth.
Are commuter towns a better investment than city centres in 2026? Neither is universally “better.” City centres tend to offer stronger liquidity and rental demand depth, while commuter towns often deliver higher yields and faster rental growth from a lower entry price. Many experienced investors hold both.
Is 2026 a good time to invest in UK property? With average UK rents and house prices both rising, and regional cities like Manchester, Leeds, Birmingham and Liverpool showing sustained regeneration investment, current market conditions remain supportive for long-term investors, though as with any investment, individual circumstances and risk tolerance should guide any decision.
Market data and statistics referenced in this article are sourced from publicly available reports by ONS, HM Land Registry, Rightmove, Savills, RICS and other recognised industry bodies, correct as of the publication date. Property investments carry risk. Capital is at risk and property values can fall as well as rise. Past performance is not a reliable indicator of future results. This article does not constitute financial advice. Independent financial advice should be sought before investing.


