Specialist Supported Housing Investment: How It Works
Supported housing investment, and specialist supported housing in particular, has quietly become one of the most talked-about income strategies in UK property, and for good reason. You buy a brand new home, it’s leased for 25 years to a registered housing provider, and the rent arrives every month without you ever finding a tenant, fixing a boiler or chasing an agent.
It’s not for everyone. If you want to be a hands-on landlord who knows your tenants and has a say in how the property is run, this isn’t it. It’s for cash buyers who want a completely passive, stress-free income and are mainly interested in the yield. In many ways, the best way to think about it is less as a property investment and more as a vehicle for a long-term, inflation-linked income that happens to be secured on a brand new property. This guide explains how specialist supported housing investment works, what returns look like, what the risks are, and how to tell a good opportunity from a poor one.
Specialist supported housing investment at a glance
Question
Quick answer
What is it?
Buying a brand new home that’s leased to a registered housing provider to house adults with long-term support needs
Who pays the rent?
The housing provider, which is funded mainly through housing benefit paid by local councils
How long is the lease?
Typically 25 years, fully repairing and insuring
What are typical net yields?
Current opportunities typically range from around 11.5% to 16% a year
What about empty periods?
The provider pays the rent whether or not the property is occupied
Does the rent rise?
Yes, usually every year in line with inflation (typically CPI + 1%)
How do you buy?
Cash only, with prices typically from around £130,000 to £300,000
What’s the main trade-off?
A smaller pool of buyers when you sell, and values based on the rent rather than the open market
What is specialist supported housing?
Specialist supported housing (SSH) is accommodation for adults with long-term care and support needs, such as people with learning disabilities, autism, physical disabilities or long-term mental health needs. It’s designed to help them live as independently as possible in their own home, with care and support provided on site or nearby.
The homes are usually adapted, with features like wider doorways, accessible bathrooms or extra space for carers. They’re leased to a registered housing provider, which houses the residents and arranges their support. It’s settled, long-term housing for people who need it, not short-term or emergency accommodation.
Demand comfortably outstrips supply. Councils across the country need more good-quality supported homes, which is why new properties continue to be built or fully refurbished for this purpose.
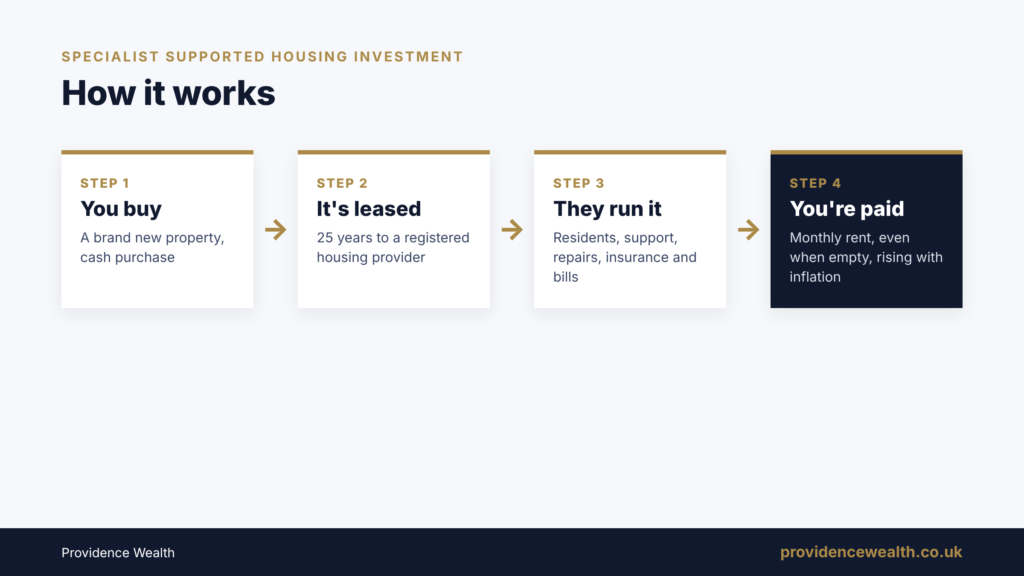
How specialist supported housing investment works
The structure is simple, which is a big part of its appeal.
You buy a brand new property. It’s either newly built or fully refurbished to the provider’s specification. You own it outright, as a cash purchase.
It’s already leased. The property comes with a 25-year lease to a registered housing provider, usually on fully repairing and insuring terms.
The provider runs everything. They place and support the residents, manage the property, and cover repairs, maintenance, insurance and bills under the lease.
You receive the rent. The provider pays you the agreed rent every month, including during any empty periods, and it rises each year in line with inflation.
The provider’s income comes mainly from housing benefit paid through local councils, with care and support funded separately. Providers are typically not-for-profit organisations, such as charities and community benefit societies, whose work is funded by government. Your rent is paid by the provider under the lease, and that funding is what sits behind it.
How it works
Returns: what specialist supported housing investment can pay
The current opportunities we work with typically offer net yields of around 11.5% to 16% a year, with prices from around £130,000 to £300,000. Because the lease is fully repairing and insuring, the net figure is close to what you actually receive: there are no service charges, letting fees or repair bills coming out of it.
The rent usually rises every year in line with inflation, typically CPI + 1%. That matters over a 25-year lease, because your income grows rather than standing still. (Our guide to property investment vs savings shows what inflation does to income that doesn’t rise.)
A simple worked example
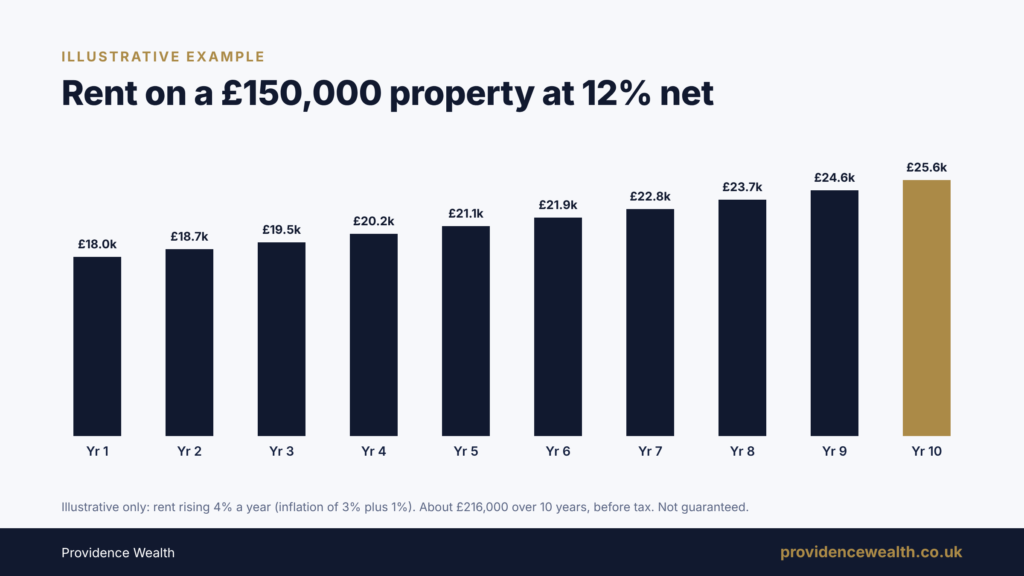
Take a £150,000 apartment with a 12% net yield, and assume annual rent increases of 4% (inflation of 3% plus 1%). These figures are illustrative only.
Year
Annual rent received
Year 1
£18,000
Year 2
£18,720
Year 3
£19,469
Year 5
£21,057
Year 10
£25,619
Total over 10 years
About £216,000
Income is before tax, and real increases will depend on inflation each year. Your own figures will depend on the specific property and lease, which is why we always go through them on a call.
Rent increases: built in
Why investors choose supported housing investment
Hands-off income. No tenant finding, no management, no repairs and no service charges under a fully repairing and insuring lease.
Long-term certainty. A 25-year lease means no tenancy turnover, and the rent is paid even if a room or property is empty.
Strong net yields. Typically 11.5% to 16% net, well above what most standard buy-to-let investments achieve.
Inflation-linked rent. Annual increases help your income keep its value over time.
Brand new stock. Every property is newly built or fully refurbished, so it starts life in excellent condition.
Social purpose. Your investment provides a settled, suitable home for someone who needs it, which is why the sector is attracting growing interest from ESG-focused and institutional investors.
What to consider before you invest
Supported housing investment is built for security, but it’s still worth understanding how it works in practice.
How secure is the rent?
Very. The rent is fixed in a 25-year lease with a registered provider whose work is funded by government, and it’s paid whether or not the property is occupied. We avoid the word “guaranteed” for any investment, but this is about as close to it as property gets.
What if a provider stops operating?
It’s a fair question, and it’s rare. Providers are established, government-funded organisations, usually charities or community benefit societies. If one did stop operating, the residents wouldn’t simply be moved out: the homes are needed, the funding stays in place, and the lease would be expected to pass to another registered provider. When you enquire, we’ll show you exactly how this is handled for the specific property and lease you’re looking at.
Selling later
Supported housing isn’t difficult to sell, but you’re selling to a specific market: other income investors and institutions rather than the open residential market. Values are based on the rent and the remaining lease, much like a commercial property. If you want the option to sell to anyone at any time, a standard residential investment may suit you better.
Cash only
Mainstream mortgage lenders don’t usually lend on this type of property, so purchases are cash only. It’s best suited to investors with funds they’re happy to commit for the long term.
Hands-off means hands-off
You won’t choose the residents, visit regularly or decide how the property is run. For most investors in this space, that’s exactly the point.
How we choose specialist supported housing opportunities
We apply the same director-level approach set out in our guide to off-plan due diligence, with extra checks specific to this sector:
The provider. Its registration, finances, funding and track record.
The lease. Length, repairing and insuring terms, rent review clauses, break clauses and what happens if the provider changes.
The residents. We focus on long-term specialist supported housing for adults with genuine care and support needs, rather than short-term or high-risk accommodation.
The property. New build or full refurbishment to the provider’s specification, in a location the local council needs.
The numbers. Whether the rent is sustainable for the provider over the full lease, not just attractive on day one.
When you enquire about a specific property, we’ll share who the registered provider is, along with example leases and contracts, so you can see exactly what you’re buying.
Specialist supported housing vs other property investments
Specialist supported housing isn’t better or worse than other property investments. It does a different job. Many of our clients hold more than one type.
Specialist supported housing
Off-plan buy-to-let
Main goal
High, steady income
Capital growth plus rental income
How you buy
Cash only
Deposit now, balance on completion, usually with a mortgage
Specialist supported housing investment: the short version
You buy a brand new property with cash, it’s leased for 25 years to a registered housing provider, and you receive an inflation-linked rent without managing anything. Current opportunities typically pay around 11.5% to 16% net. It suits investors who want a completely passive income and are happy with a specialist resale market and a cash purchase.
How Providence Wealth helps
Director-level due diligence. Every specialist supported housing opportunity we offer has been reviewed by a director, including the provider and the lease.
Real numbers on a discovery call. We’ll walk you through the yield, the lease terms and the assumptions behind them for a specific property.
Independent legal support. We introduce you to solicitors who know this type of purchase and act only for you.
Free limited company setup. If you’re buying through a company, we’ll help you set it up at no cost. Our guide to buying property through a limited company explains the pros and cons.
Interested in finding out more? Book a no obligation call with our Managing Director, Sam who will talk you through the opportunity and current availability in more detail.
For cash buyers who want a long-term, completely hands-off income, it’s a strong option. Net yields typically range from 11.5% to 16%, the rent rises with inflation and it’s paid even during empty periods. It isn’t designed for investors who want to be hands-on landlords or sell to the open market.
Who pays the rent?
The registered housing provider pays your rent under the lease, every month, whether or not the property is occupied. The provider is funded by government, mainly through housing benefit paid by local councils.
Can I get a mortgage on specialist supported housing?
Usually not. Mainstream lenders don’t typically lend on this type of property, so purchases are cash only.
What happens if a housing provider stops operating?
It’s rare, as providers are established, government-funded organisations. If one did stop operating, the lease would be expected to pass to another registered provider, because the residents still need their homes and the funding remains in place. We’ll walk you through how this works for the specific lease you’re considering.
Can I sell a specialist supported housing property?
Yes, but usually to other income investors or institutions rather than the open market. The value is based mainly on the rent and the remaining lease, so a property with a strong provider and long lease is generally easier to sell.
Who lives in specialist supported housing?
Adults with long-term care and support needs, such as learning disabilities, autism, physical disabilities or long-term mental health needs, who are supported to live as independently as possible.
This article is for general information only and does not constitute financial, legal, tax or investment advice. Yields, rent increases and property values are not guaranteed. Capital is at risk. Please take independent advice before making any investment decision.
Market data and statistics referenced across this website are sourced from publicly available reports by ONS, Land Registry, Savills, RICS, and other recognised industry bodies. All figures are provided for indicative purposes only. Property investments carry risk. Capital is at risk and property values can fall as well as rise. Past performance is not a reliable indicator of future results. This website does not constitute financial advice. Independent financial advice should be sought before investing.
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behaviour or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
Get our full guide to off-plan investment, real numbers, our due diligence process, and what actually happens from first call to completion. Opens straight in your browser, nothing to download.